New sustainability reporting obligations in France: what’s new?
Navacelle contributes to The Legal Industry Reviews' fifth edition about the transposition of the Corporate Sustainability Reporting Directive (CSRD) in France by a government order of 6 December 2023 introducing new reporting obligations in terms of sustainability.
France is the first Member State to transpose the Corporate Sustainability Reporting Directive by an order issued by the Government on 6 December 2023. This order aims at replacing the current extra-financial performance statement (déclaration de performance extra-financière or DPEF) system by a sustainability reporting, as well as to simplify and clarify other CSR reporting mechanisms.
***
Directive (EU) 2022/2464, known as the CSRD or Corporate Sustainability Reporting Directive,[1] introduced an obligation for certain companies to disclose sustainability information. It replaces Directive 2014/95/EU related to the extra-financial performance statement (DPEF) and was transposed in France on 6 December 2023 by the Order n°2023-1142 which introduces new sustainability reporting obligations (I) and a new audit system (II).
I. Many French companies will have to comply with new reporting obligations in the near future, particularly regarding sustainability
The Order harmonized CSR reporting obligations within the French Commercial Code, particularly regarding (i) the general reporting in the management report (rapport de gestion) by listing the information it must contain,[2] such as key performance indicators of a financial and non-financial nature,[3] and (ii) specific reporting for companies operating Seveso “high-threshold” facilities[4] on their risk management,[5] as well as for companies operating in the extractive and primary forest exploitation sectors on some payments made to Countries or territories above 100.000€.[6]
Above all, the main innovation introduced by the Order is the requirement for large companies, small and medium listed companies as well as for certain companies established outside the European Union or the European Economic Area which have a branch in France, to disclose sustainability information.[7] Such information is defined as information that “makes it possible to understand the impact of the company’s activity on sustainability issues, as well as the way in which these issues influence the development of its business, performance and position”, it being specified that “sustainability issues include environmental, social, governance and employee matters”.[8]
II. Audit of sustainability reporting will be open to a wider range of auditors, under the supervision of the Haute autorité de l’audit
The Order provides that sustainability information disclosed by large companies and listed small and medium companies will be audited by a statutory auditor or an independent third-party, and that information disclosed by foreign companies with a branch in France will be subject to a report by persons or firms authorized under the law applicable to the company, a statutory auditor or an independent third-party, expressing their opinion on the compliance of the information provided.[9]
As a result, rules governing the profession of statutory auditors have been amended to reflect this new mission of auditing sustainability information,[10] and new rules have been introduced for “sustainability information auditors” (which may include lawyers) working within independent third-parties.[11]
These new rules are based on the principle of identical rules, which means that rules applicable to sustainability information auditors are the same as those applicable to statutory auditors, with only limited exceptions,[12] to ensure fair competition, to enable them to work together, to offer stakeholders the certainty of the same requirements for each of them, and to enable a homogeneous presentation of their reports.[13]
Finally, the Order provides that statutory auditors and sustainability information auditors working for independent third-parties will operate under the supervision of an authority named the Haute autorité de l’audit(H2A), which main tasks will be to register the latter, to keep the list of registrants, to monitor statutory auditors, independent third-parties and sustainability information auditors as well as to impose penalties.[14]
Related content
Press review
16 October 2026
Press Review – Week of 12 October 2026
This week, the press review covers the publication by the French Anti-Corruption Agency of an educational guide aimed at raising...
Press review
11 September 2026
Press Review – Week of 7 september 2026
This week, the press review covers the publication by the French Anti-Corruption Agency of a practical guide on third-party evaluation...
Video
8 September 2026
Analysis of the French Anti-Corruption Agency Sanctions Commission’s Decision of 9 July 2026
Julie Zorrilla, partner at Navacelle, spoke alongside François Malan during a webinar hosted by the Cercle de la Compliance, dedicated...
Analysis
7 September 2026
Publication by the French Anti-Corruption Agency (AFA) of a practical guide on the internal whistleblowing...
On 16 July 2026, the French Anti-Corruption Agency (AFA) published a practical guide titled “Implementing an Internal Whistleblowing System and...
Press review
4 September 2026
Press Review – Week of 31 August 2026
This week, the press review looks at covers the entry into force of the financial penalties regime applicable to ultra-fast...
Press review
21 August 2026
Press Review – Week of 21 August 2026
This week, the press review looks at the publication of a French Prime Minister’s directive aimed at strengthening the fight...
Press review
31 July 2026
Press Review – Week of 31 July 2026
This week, the press review looks at TotalEnergies’ appeal against the ruling on the duty of vigilance, the removal of...
Press review
24 July 2026
Press Review – Week of 24 July 2026
This week, the press review highlights the Paris administrative court’s decision concerning whistleblower status in the case involving Édouard Philippe,...
Analysis
23 July 2026
The AFA’s Sanctions Committee imposes its first financial penalties
The Sanctions Committee of the French Anti-Corruption Agency (AFA) made use of its enforcement powers for the first time in...
Event
13 July 2026
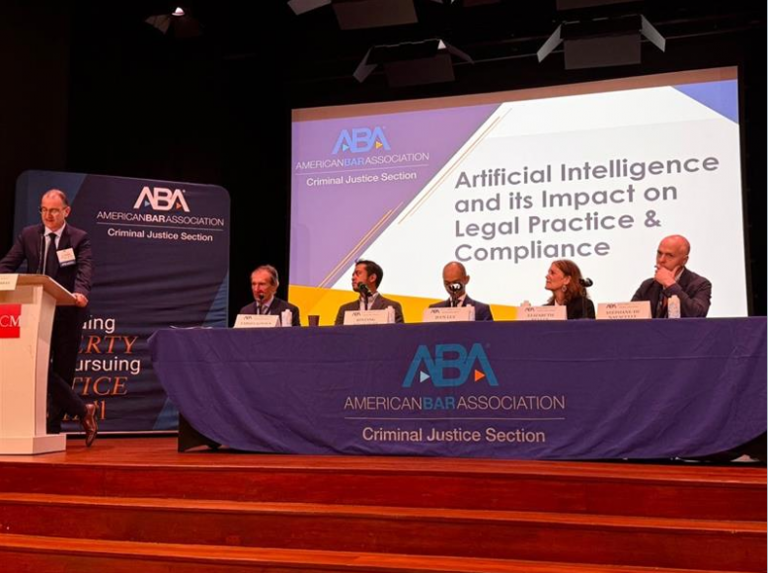
2026 Global White Collar Crime Institute-Singapore Plenary Session II: Artificial Intelligence and its Impact on...
Stéphane de Navacelle spoke at the 2026 Global White Collar Crime Institute in Singapore, alongside Zvi Gabbay, Fabio Cagnola, Bintang...
Press review
10 July 2026
Press Review – Week of 10 July 2026
This week, the press review looks at the publication of the French Antibribery Agency (AFA)’s 2025 activity report, Marine Le...
Publication
7 July 2026
Overview of developments in ethics and compliance in France and in Europe
The EU is stepping up its fight against money laundering and corruption, particularly through the AMLA. In France, this is...
We use cookies to optimize our website and our services.
Functional
Always active
The technical storage or access is strictly necessary for the legitimate purpose of enabling the use of a specific service explicitly requested by the subscriber or user, or for the sole purpose of carrying out the transmission of a communication over an electronic communications network.
Préférences
The technical storage or access is necessary for the legitimate purpose of storing preferences that are not requested by the subscriber or user.
Statistics
The technical storage or access that is used exclusively for statistical purposes.The technical storage or access that is used exclusively for anonymous statistical purposes. Without a subpoena, voluntary compliance on the part of your Internet Service Provider, or additional records from a third party, information stored or retrieved for this purpose alone cannot usually be used to identify you.
Marketing
The technical storage or access is required to create user profiles to send advertising, or to track the user on a website or across several websites for similar marketing purposes.